A footprint we can explain.
A carbon plan earns its value when the company can connect the figures with its activities and the decisions it can change. NEUVIOR’s retained April 2026 document sets out a 2045 direction and an initial operating plan. The current review makes the next evidence requirements clearer, while keeping the original record intact.
Start with the plan already retained.
The eight-page document identifies NEUVIOR Pharmaceuticals Ltd as its reporting entity, uses an operational-control approach and records net zero by 2045 across Scope 1, Scope 2 and all relevant Scope 3. It is dated 10 April 2026 with a stated review date of 10 April 2027. Its declaration names Varun Sharma, Director, as approving publication.
The reviewed site files do not supply a separate board minute or signed carbon declaration. The redesigned companion therefore reports the document’s existing wording without creating or backdating an approval. It is a current-position review draft, rather than a replacement declaration.
An unfinished inventory must remain visible.
The retained plan does not publish a completed baseline-year or current-year emissions total. Its scope assessments and value-chain mapping remain work to complete. This means the plan should not be described as a fully quantified, independently verified CRP or evidence of procurement compliance.
Missing records do not establish zero emissions. The inventory needs to assess relevant sources, explain exclusions and retain the basis of estimates. That work gives the company a reliable starting point and makes future changes easier to interpret.
Build the reporting boundary carefully.
The proposed next exercise should confirm the entity, reporting year, operational-control boundary and whether the business has changed since April. A global boundary means accounting for all relevant operations of the entity; it is not a claim of international offices or campuses.
Screen all GHG Protocol Scope 3 categories for relevance. Computing, devices, purchased services, travel and workspaces are practical starting points for evidence collection, while direct emissions and other sources must still be considered. Materiality and the calculation method should be documented.
Carbon reporting evidence
Can each footprint figure be traced to its activity?
The retained carbon plan records direction while the first complete inventory remains unfinished. Follow the chain a future figure would need: source activity, an appropriate boundary, a stated calculation and an accountable review. This makes the difference between missing data, changed methodology and a measured operational reduction easier to examine.
Editorial decision model, not measured NEUVIOR results.
The first useful total needs a visible evidence chain.
The company can prioritise relevant records and explain where estimation remains necessary. This produces a more dependable basis for management than treating uncollected information as a negligible category. The inventory should stay connected to the operating activity it describes, including where that activity has changed.
Assign evidence collection and document the reporting choices.
Source activity record
Invoices, service records and travel information can establish activity where they match the reporting entity and period. Missing records do not establish zero emissions. The proposed inventory should identify the source needed and preserve any estimation assumptions for later review.
- Allocate the activity
Activity quantity, unit, date and supporting source record.
A useful next stepChoose the missing record most likely to change an important category.
A carbon figure becomes useful when its activity, boundary, method and approval can all be explained.
Make reductions reviewable.
The April plan describes operational measures such as virtual working, travel choices, efficient computing and extending device life. A review should distinguish measures demonstrably in effect from those still being embedded. Record owners, evidence and the way any reduction would be checked.
Changing a reporting boundary or conversion factor can change the inventory without changing operations. A future report should explain those differences. This protects the usefulness of the numbers for management and for anyone assessing the company’s supplier-readiness position.
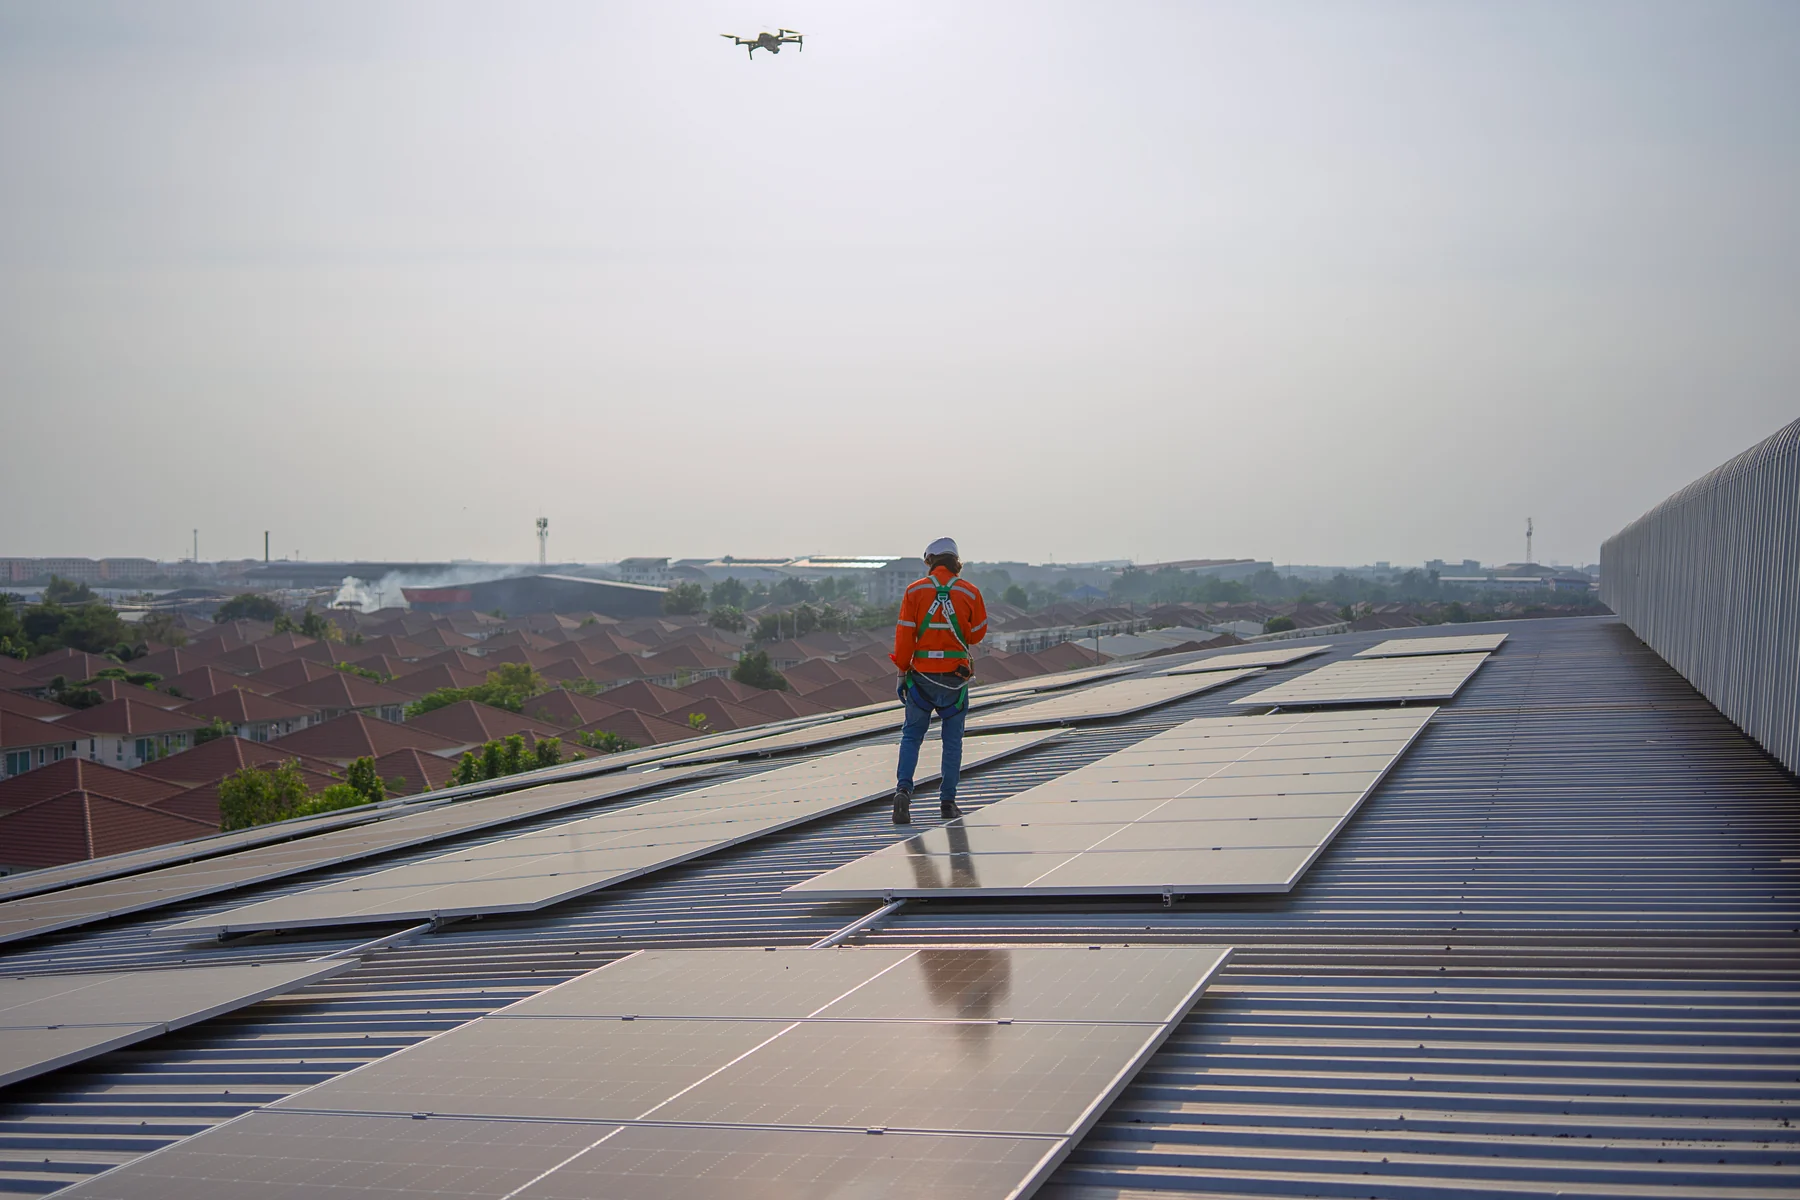
An energy measure needs its own activity records, system boundary and evidence of effect. External rooftop-photovoltaic photography provides operating context; it is not a NEUVIOR property, emissions baseline or measured reduction.
acinar13 · Solar Panel Installation on a Commercial RooftopEnvato Elements commercial licence
Source and image notes
Full frame retained; EXIF orientation honoured, proportionally resized and encoded as WebP. No crop, creative colour grading, compositing or generative changes. ICC-managed conversion from Display P3 to sRGB for consistent display.
Prepare for the applicable NHS route.
NHS procurement requirements depend on the contract, route and commencement date. Guidance before April 2027 distinguishes full CRPs from lower-value Net Zero Commitments; the published April 2027 policy uses two CRP tiers. The wider tier brings global reporting across all relevant scopes. A particular tender’s conditions must still be checked.
Evergreen preparation is related but separate. Level 2 reporting and the Level 3 ambition require their own evidence. The reviewed records do not establish a completed assessment, independent target validation or verified emissions.